A few months ago, I was speaking to an investor who had been with me for several years. He came to our meeting with a list on his phone.
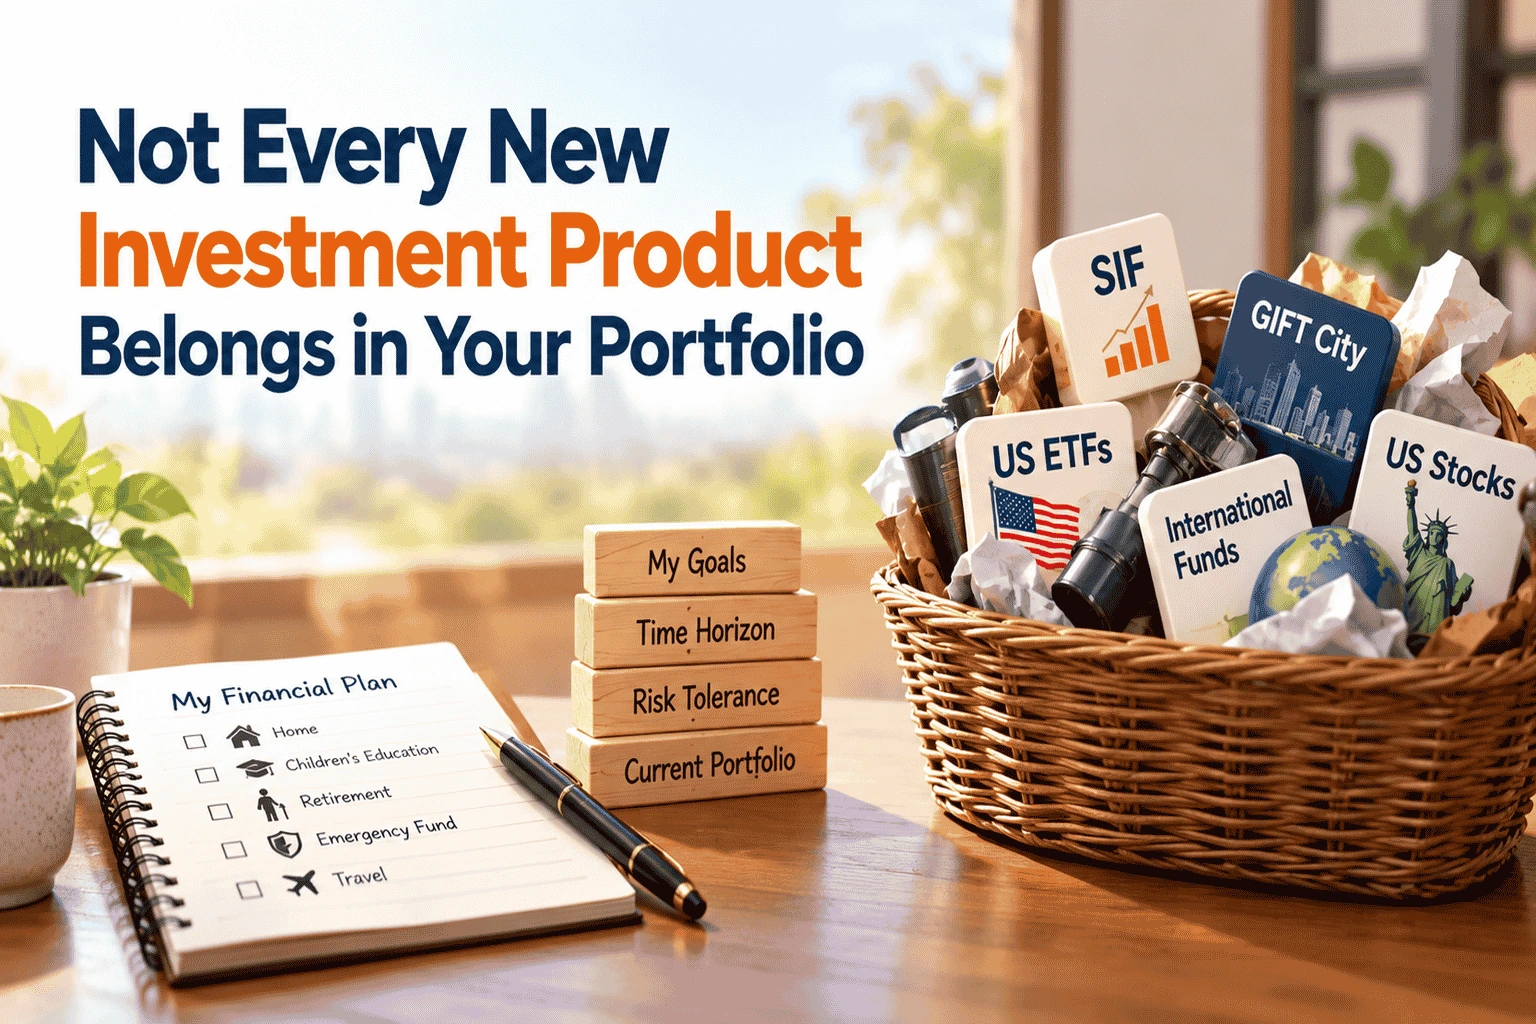
“SIF.”
“GIFT City.”
“US ETFs.”
“International funds.”
“US Stocks.”
He had watched several videos, read a few articles, and followed some financial creators online. By the time we met, he was convinced that his portfolio was missing something.
“I think I am too conservative,” he told me. “Everyone seems to be investing in these new products. Should I also start?”
I asked him a simple question.
“What is the goal for which you want to add these investments?”
There was silence. He did not have an answer.
But this conversation stayed with me. I have noticed this more and more over the years as a mutual fund distributor. The investment world is becoming more interesting, more sophisticated and, frankly, noisier.
We are hearing about Specialized Investment Funds, investments through GIFT City, ETFs, international ETFs, US markets, alternative strategies, and several other products.
There is nothing inherently wrong with these products. Many of them have been created to solve genuine investor needs. SIFs, for example, are designed to offer more sophisticated investment strategies and sit between traditional mutual funds and PMS in the regulatory framework.
GIFT IFSC has also expanded the range of investment possibilities available through its regulated ecosystem, including ETFs and other fund structures.
Similarly, international investing and overseas ETFs can provide access to markets and opportunities that may not be available in India. There are, however, regulatory limits governing overseas investments by mutual funds.
We live in an age where discovering an investment idea takes only a few seconds. You see someone explaining how they invested in a US ETF. You watch another video about a new SIF strategy. Someone talks about GIFT City and its growing ecosystem. The product sounds interesting and the argument sounds logical. Now, suddenly, you want that product in your portfolio.
But this is not how investing should work. You should not discover a product first and then find a reason to invest in it.
You should start with your financial goal. What are you trying to achieve? How much money do you need? When do you need it? How much volatility can you genuinely tolerate? What is already present in your portfolio? And only then ask whether a particular product has a role to play.
This is especially important because complexity can sometimes create the illusion of sophistication.
A portfolio does not automatically become better because it contains more products. A portfolio with five different investment categories is not necessarily better than one with three.
An international ETF is not automatically better because it gives you access to the US market. A SIF is not automatically better because the strategy is more sophisticated. And investing through GIFT City is not automatically necessary just because it is a new avenue.
The right product solves a problem you actually have, and your financial plan should address your needs.
Coming back to my investor with questions, we eventually went through his goals, existing investments, time horizons and risk tolerance. And interestingly, he did not need most of the products he had come asking about
Being a good investor is knowing which products you need, which ones you don’t, and why.
Shreedhara is the Founder & Director of Ara Financial Services Pvt. Ltd. He has an experience of over 2 decades in Financial Service Industry with majority of it in guiding individuals and institutions on their investments requirements.