A lot of investors are unhappy right now. Not because the market crashed, but because it has not moved.
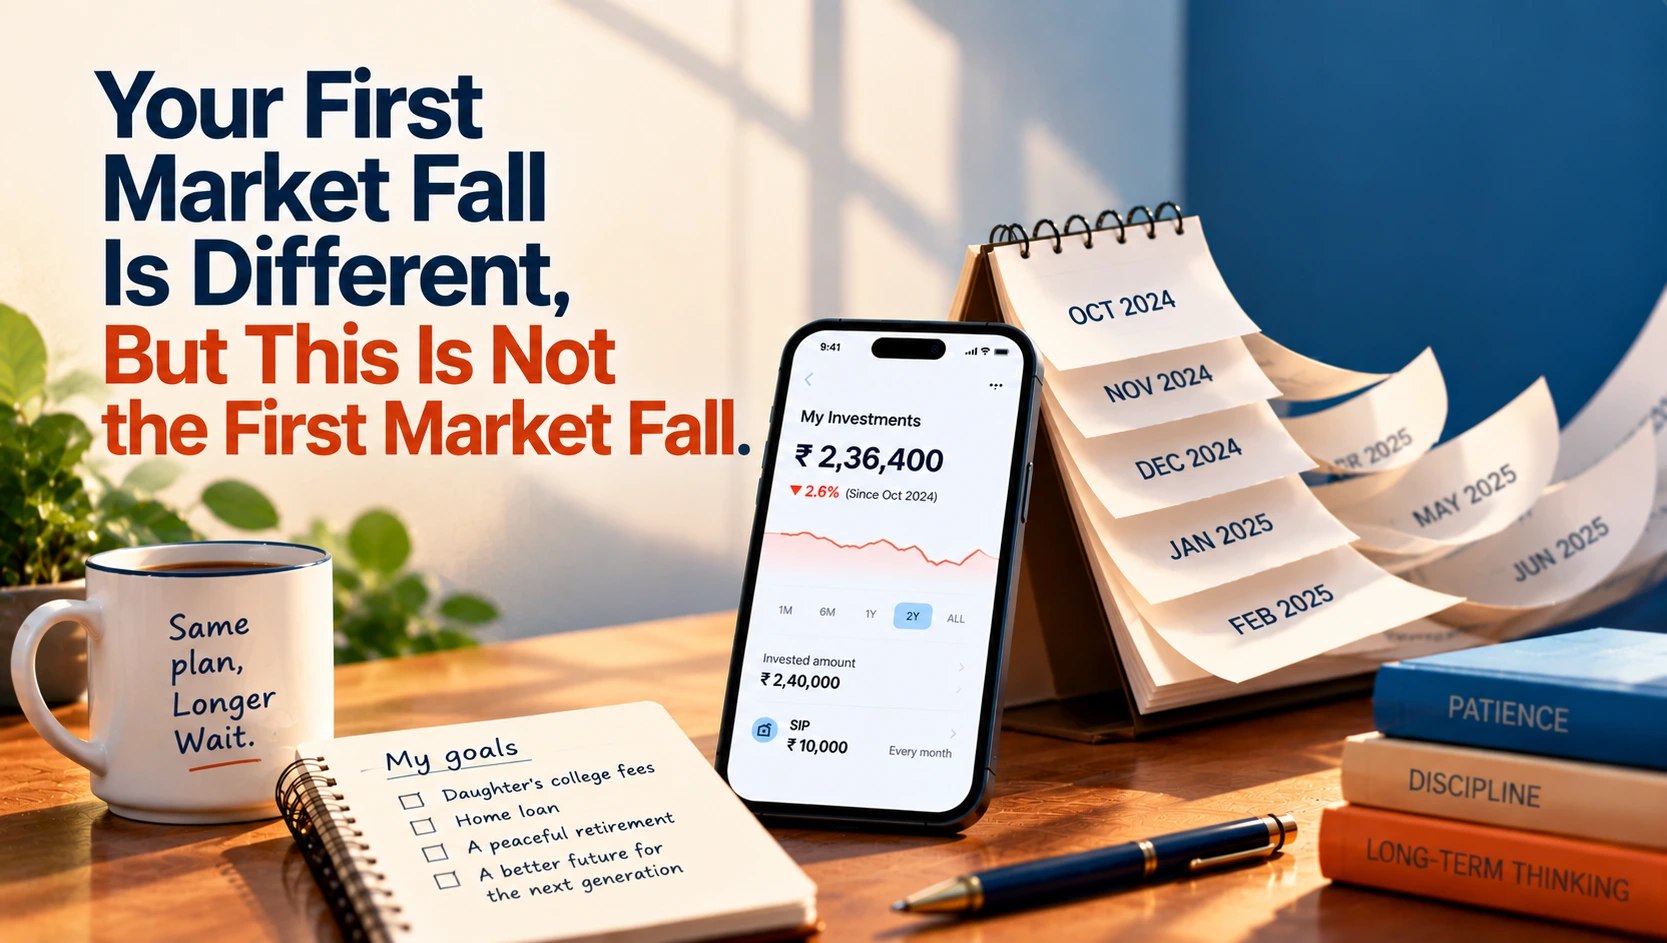
Say you started a ₹10,000 monthly SIP in the broad market (the Nifty 500) in October 2024. Two years later, you have put in ₹2.4 lakh, and it is worth a little less than that. Two years of opening the app and seeing the same number, or a slightly smaller one.
Your plan has not failed. It is just a long wait, and long waits test your patience more than your nerves. Was this a mistake? Would an FD have been better?
If this feels new, it probably is. About four in five demat accounts in the country were opened after March 2020. Most of them have known a market that largely went up.
Reading about it is not the same as living it
You can watch every swimming video on YouTube. The first time your feet don’t touch the floor of the pool, you still learn something no video could teach.
Markets are no different. Reading about a fall is easy. Watching your own hard-earned money go nowhere for two years is not.
Look in the rear-view mirror
| Episode | Peak to bottom | Fall | Time spent below the old peak |
| Harshad Mehta scam | Apr 1992 to Apr 1993 | 54% | About 2 years 3 months |
| Dot-com bust and Ketan Parekh scam | Feb 2000 to Sep 2001 | 56% | About 3 years 11 months |
| Global financial crisis | Jan 2008 to Mar 2009 | 61% | About 2 years 10 months |
| COVID-19 crash | Jan 2020 to Mar 2020 | 38% | About 10 months |
Basis. Sensex daily closing values, closing peak to closing bottom. Source: DSIJ analysis of BSE Sensex closing data
Between 1992 and 2020, the Sensex fell 20% or more nine times.
Many young investors watched Scam 1992 as a web series. For their parents, it was the news which they experienced firsthand. The Sensex fell 54% within a year. Then came the dot-com crash and the Ketan Parekh scam (56%), 2008 (61%) and COVID (38%).
The 1992 peak was not built on corporate earnings. It was built on a scam, and a rise built on a scam cannot last. The market had to correct, and it took years for real business growth to catch up with those inflated prices. Along the way came more shocks, including the dotcom bust and the Ketan Parekh scam. Events like these may never repeat, but it is worth knowing that they have happened. Then, from the end of 2002, the market rose about six times in five years. History makes no promises, but it does show that long, boring phases are part of the journey.
Ask the people who were there
A table shows how far the market fell. It cannot show how it felt.
So, ask your parents, a senior colleague, or whoever you treat as your money guru. Someone who is in their mid-fifties today was in their mid-twenties when the Harshad Mehta bubble burst. They stood exactly where you are.
Ask them what 2008 felt like, with a home loan EMI and school fees to pay. Did they stop their SIPs? Did they sell? What would they do differently?
Then just listen.
Now look at your own numbers
| Period | Point-to-point return | SIP return (XIRR)* |
| 23 Mar 2020 to 30 Sep 2026 | +253.55% | 10.26% |
| 31 Dec 2020 to 30 Sep 2026 | +91.63% | 7.91% |
| 23 Mar 2020 to 30 Sep 2024 | +288.36% | 25.36% |
| 31 Dec 2020 to 30 Sep 2024 | +110.49% | 23.99% |
| 1 Oct 2024 to 30 Sep 2026 | -9.06% | -2.60% |
“Point-to-point returns are absolute, not annualised. SIP returns are annualised (XIRR) for a monthly SIP (on 5th of every month) over the period shown. Index: Nifty 500 (price Index). Index returns are not indicative of any scheme’s returns.”
Even after two dull years, someone who started near the COVID low has seen the broad market grow about three and a half times. Their SIP has earned about 10% a year.
Yes, the same SIP showed about 25% in September 2024. But the 10% is not the problem. The 25% was the exception that felt like the rule.
Your goal runs on its own clock
The market does not know you are saving for your daughter’s college fees in 2038, the down payment on a home in 2031, your son’s wedding in 2040, or your own retirement in 2050. So before you react, ask three questions. Has my goal changed? Has my time horizon changed? Has my reason for investing changed?
If the answer to all three is no, the market has changed the price, not your plan. If any is yes, review it calmly against your goals, not the headlines.
Twenty or thirty years from now
Picture your son or daughter in their mid-twenties, sitting across the table from you. Phone in hand. Worried. Probably it is their first market fall.
If you live through this phase with patience, you will be able to say:
“Beta, I have seen this before. Stay calm. Let’s look at the plan.”
So save this note. Not for this fall. For that evening.
The money you leave your children is one inheritance. The calm you leave them may be worth more.
Shreedhara is the Founder & Director of Ara Financial Services Pvt. Ltd. He has an experience of over 2 decades in Financial Service Industry with majority of it in guiding individuals and institutions on their investments requirements.