Consider that you start investing ₹5,000 every month. A year later, your salary increases, but your SIP remains the same. Over time, your income grows, your expenses change, and your financial goals get bigger. Yet, your monthly investment continues at ₹5,000, and you do not increase it to the fullest potential of your revised salary.
Step-Up SIP helps you gradually increase your monthly investment and potentially build a much larger corpus over the long term.
Let’s understand how it works.
What Is a Step-Up SIP?
A Step-Up SIP, also called a Top-Up SIP, allows you to increase your monthly SIP contribution at regular intervals, usually once a year.
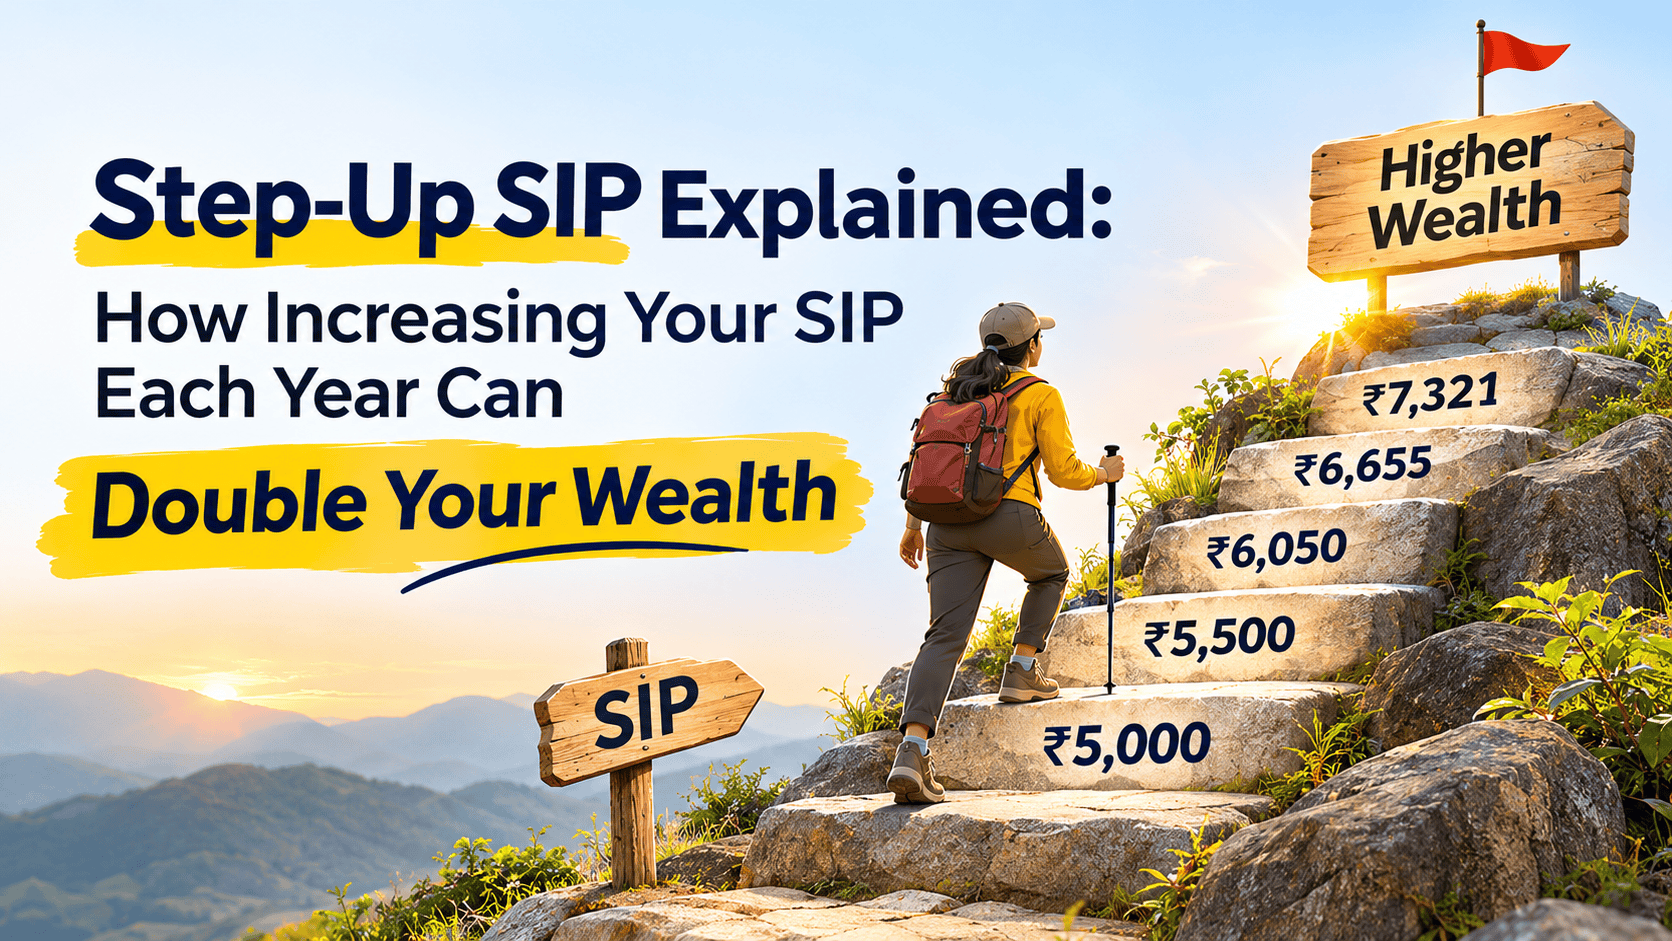
For example, suppose you start with a monthly SIP of ₹5,000 and decide to increase it by 10% every year.
- Year 1: ₹5,000 per month
- Year 2: ₹5,500 per month
- Year 3: ₹6,050 per month
- Year 4: ₹6,655 per month
- Year 5: ₹7,321 per month (approximately)
Without a significant jump in your salary too, you can increase your investment gradually. This approach works particularly well for salaried individuals whose incomes tend to increase over time.
How Can a Step-Up SIP Help You Build More Wealth?
Let’s compare two investors.
Both invest in mutual funds for 20 years and assume an annualised return of 12% for illustration. Investor A continues investing ₹5,000 every month. Investor B starts with the same amount but increases the SIP by 10% every year.
| Particulars | Investor A: Regular SIP | Investor B: Step-Up SIP |
| Initial monthly SIP | ₹5,000 | ₹5,000 |
| Annual SIP increase | Nil | 10% |
| Investment period | 20 years | 20 years |
| Total amount invested | ₹12 lakh | ₹34.4 lakh |
| Estimated final corpus | ₹49.46 lakh | ₹98.5 lakh |
Note: Illustrative calculations assume monthly investments, a 12% annualised return, and a 10% annual increase in the SIP amount. Actual returns will vary, and mutual fund investments do not guarantee these outcomes.
Do you notice the difference? By increasing the monthly contribution gradually, Investor B could accumulate a substantially larger corpus.
However, there is an important point to remember: Investor B also invests significantly more money over the 20 year period. The larger corpus is not simply the result of better returns; it also reflects the higher contributions and the power of compounding.
A Step-Up SIP can help you build wealth faster, but the outcome depends on your contributions, investment duration, and actual returns.
How Much Should You Increase Your SIP Every Year?
There is no fixed percentage that works for everyone. A 5%, 10%, or 15% annual increase may be appropriate depending on your income growth, expenses, and financial commitments.
Here is a simple and practical approach:
1. Link your SIP increase to your income. If your salary increases, consider increasing your SIP by a manageable amount rather than spending the entire increment.
2. Keep your financial priorities in mind. Build an emergency fund, manage expensive debt, and account for essential expenses before increasing your investments.
3. Choose a sustainable increase. An ambitious Step-Up SIP that you cannot maintain may be less useful than a smaller increase you can follow consistently. Withdrawal from the investment due to an unsustainable increase may upset other priorities too.
4. Review your plan annually. Your income, family responsibilities, and financial goals may change. Adjust your investments accordingly.
Is a Step-Up SIP Right for You?
A Step-Up SIP can be particularly useful if you are early in your career, expect your income to grow, or are working towards long-term goals such as retirement or your child’s education.
As mutual fund distributors, we believe investing should evolve with your life. Your income may grow over the years, and your investments should grow along with it. A step-up SIP may not suit everyone, and that’s perfectly fine. The key idea is to raise your SIP whenever you can. Ideally, review it once a year, or whenever your income changes.
The key is simple: Plan to increase your investments as your financial capacity improves. A small increase every year may seem insignificant today, but over a long investment horizon, it can make a meaningful difference to your financial future.
Shreedhara is the Founder & Director of Ara Financial Services Pvt. Ltd. He has an experience of over 2 decades in Financial Service Industry with majority of it in guiding individuals and institutions on their investments requirements.