During my interactions with young professionals in their first year of work, I have started to see an interesting shift in how many of them think about mutual funds. In one such meeting, curiously, I asked Aryan why he chose a direct mutual fund. The answer was quick and straightforward: “Why should I pay a commission when I can invest myself?” My expectation of the answer was “this mutual fund is best suited for my goal” or something along those lines.
My first thought was that yes, absolutely, it sounds logical. It is also true that direct plans have lower expense ratios because they do not include distribution expenses or commissions. SEBI itself describes direct plans as suitable for investors who are comfortable doing their own research and managing their investments themselves.
But after thinking more deeply, I have some thoughts to share with you today.
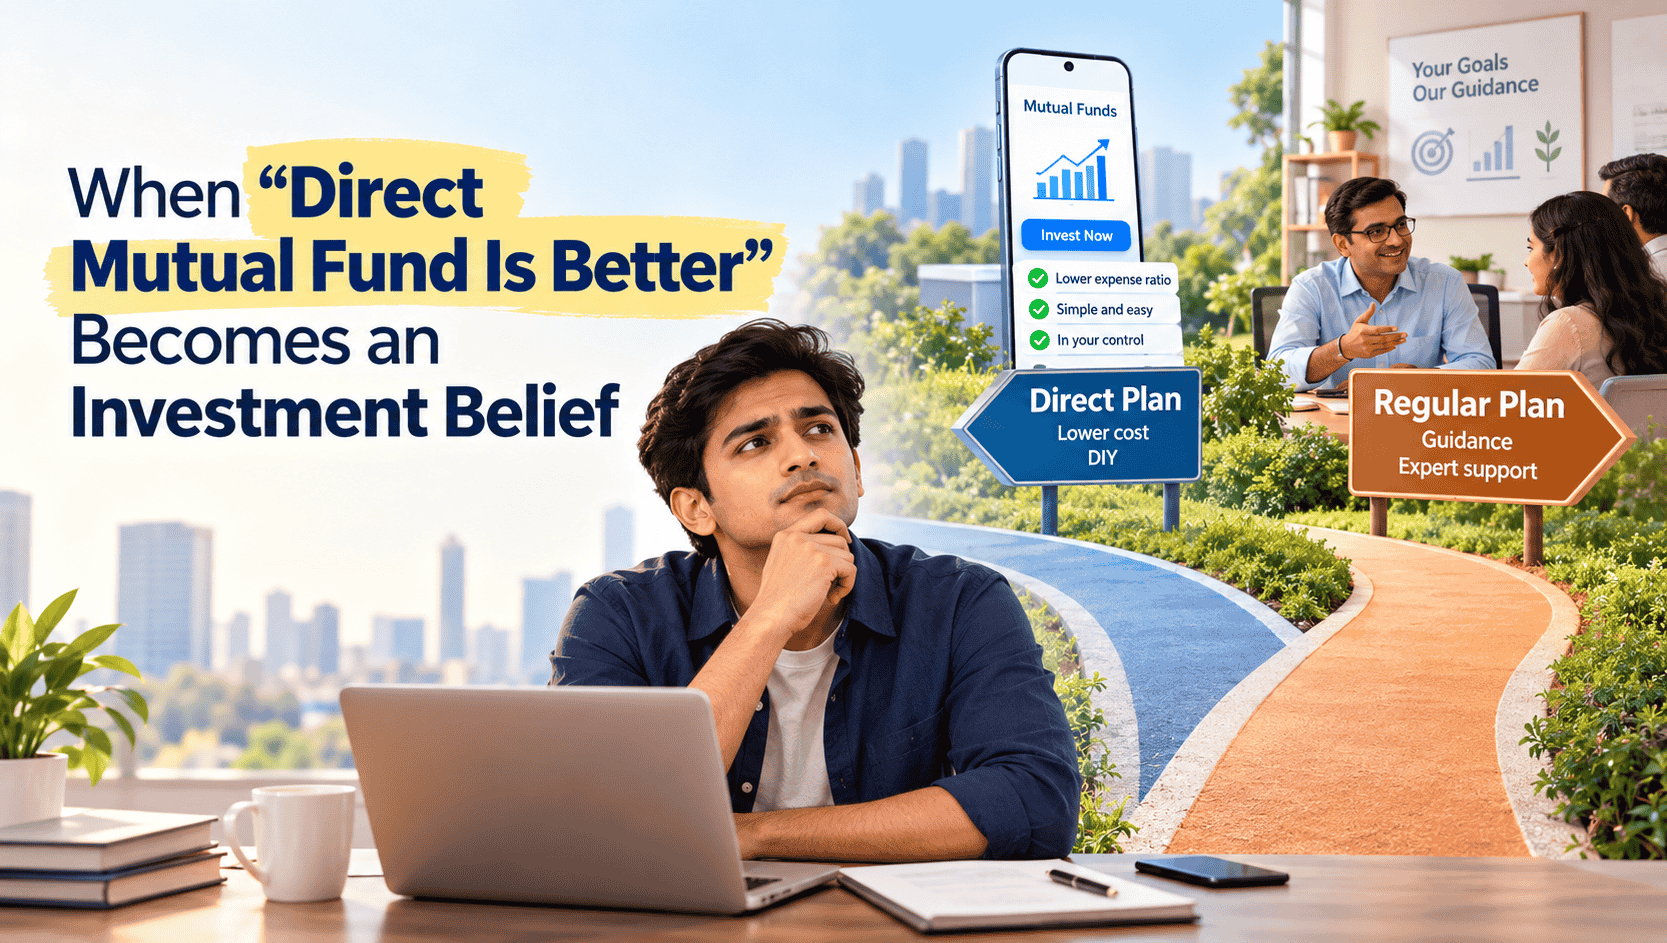
Regular plans have increasingly been portrayed as an unnecessary cost. Direct plans have become a badge of being financially savvy. And social media has made the conversation even simpler: “Why pay 1% when you can save it?” The condition for whom a direct plan is best suited is not given the deserved importance.
SEBI approved a separate direct plan structure in 2012 to promote direct investment, with a lower expense ratio for investors who chose to invest without a Mutual Fund distributor. But the mutual fund industry of that period was very different from what we see today. The cost structures, regulations, fund sizes, and distribution ecosystem have changed significantly over the years. SEBI has also progressively revised the framework governing total expense ratios.
Today, when investors look at the difference between a regular plan and a direct plan, the difference in expense ratio is visible. The value of incidental advice or guidance is not clearly evident. That creates an interesting behavioural problem.
Imagine two investors. Investor A chooses a direct plan because she understands asset allocation, knows why she has selected a particular fund, reviews her portfolio periodically, understands risk, knows when not to react, and has the discipline to continue investing through difficult markets. Investor B also chooses a direct plan. But the decision is based mainly on historical returns and a lower expense ratio. Both investors are in direct plans.
But their investment experience can be completely different.
An investor may choose last year’s best-performing fund because the return chart looks attractive. The following year, another fund takes the lead. The investor switches. A few months later, the market corrects, and the investor stops the SIP. After a prolonged period of underperformance, the investor exits completely.
There is amount mentioned on the mutual fund statement saying, “cost of poor decision- making”. Yet that cost can be far higher than the expense ratio difference.
I am not presenting the argument that regular plans are always better. A knowledgeable DIY investor who genuinely understands investing may have little need for a distributor. If an investor can select suitable products, construct an appropriate portfolio, monitor it, rebalance it and, most importantly, stay disciplined through different market cycles, the lower cost of a direct plan can be effective.
But the word “DIY” itself deserves some questioning. Doing it yourself is not the same as knowing what you are doing. Buying a mutual fund through an app is easy. Understanding why you own it is harder. Looking at a five-year return number is easy. Understanding whether that return came with risks that are appropriate for your goal is harder. Stopping an SIP is just a few clicks. Deciding whether you should stop it is a completely different exercise.
This is particularly relevant as investing becomes increasingly app-driven and younger investors enter the market. Platforms have made investing wonderfully accessible. But accessibility can sometimes create the illusion that investing itself is simple.
Along with considering the brokerage amount that needs to be paid, we should also value what value you are getting in return. A Mutual fund distributor who provides guidance, helps with goal-based allocation, explains risks, prevents unnecessary switching, provides portfolio reviews, and acts as a behavioural anchor is providing something that cannot be captured by comparing two expense ratios. Of course, the quality of that service matters. Investors should question the value they receive. They should understand how a distributor is compensated and whether the service they receive justifies the arrangement.
But reducing the entire regular-plan discussion to “commission equals loss” is an oversimplified way of looking at investing.
In investing, the highest cost is not always the cost you can see. Sometimes, it is the cost of a decision you should never have made.
Shreedhara is the Founder & Director of Ara Financial Services Pvt. Ltd. He has an experience of over 2 decades in Financial Service Industry with majority of it in guiding individuals and institutions on their investments requirements.