Till 2023: The India Story Was Easy to Believe
Till 2023, India was the market no global investor wanted to be without. The question abroad was not whether to own Bharat, but how anyone could justify being underweight Bharat.
The returns made this feel obvious. For the three years till December 2023, the Nifty 50 TRI compounded at 17.24% a year, the Nifty Midcap 150 TRI at 30.64% and the Nifty Smallcap 250 TRI at 34.26%.
Exceptional periods come with a bill. When prices run far ahead of earnings, part of the future gets borrowed. Valuations stretch, expectations run ahead of what businesses can deliver, and the years that follow do some of the repaying. The mistake is not in enjoying those years, but in assuming that they will keep coming, year after year.
The Market Did Not Break. Its Rhythm Changed.
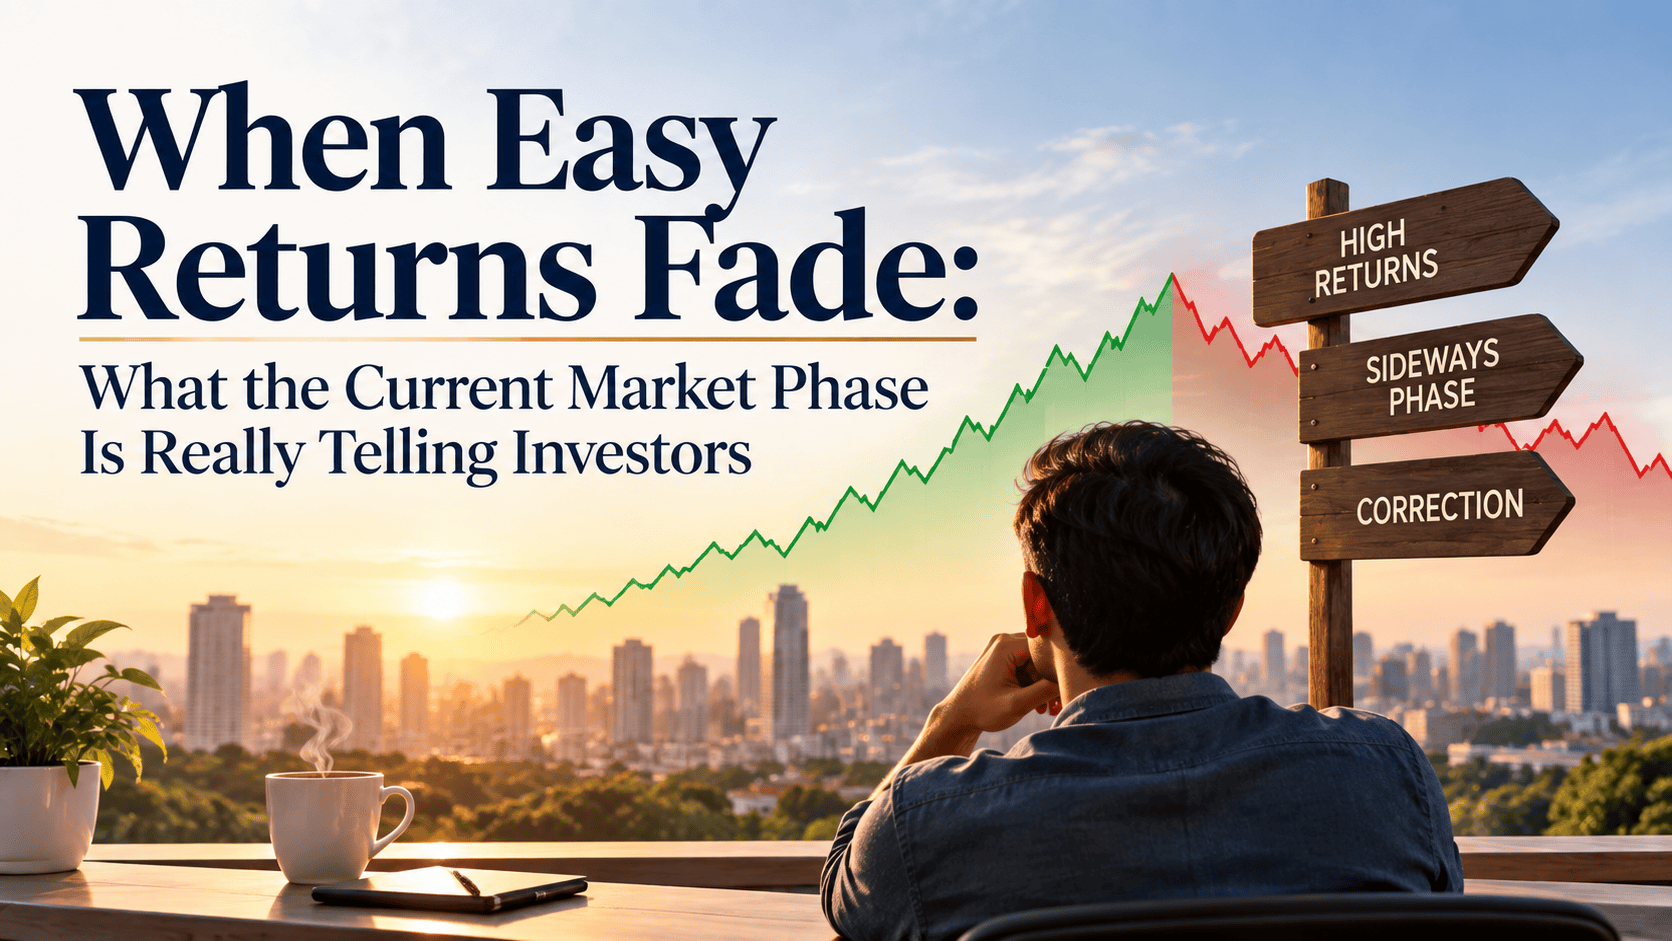
The rally stalled in September 2024, when the Nifty touched 26,277. The index took fifteen months to climb back to that level, and when it finally did, in January 2026, it managed a new high less than 0.4% above the old one before reversing. On 30 September 2026, the index closed at 22,620, nearly 14% below its September 2024 peak, with almost all of that decline coming in 2026.
Markets correct in two ways. A value correction is quick and loud: prices fall until valuations look reasonable again. A time correction is slow and quiet: prices drift sideways, sometimes for years, while earnings catch up with the valuations. The last two years have been largely a time correction, with a sharp dose of the value correction in 2026.
A time correction is often harder to live through. A crash at least arrives with a headline. A time correction offers only month after month of statements that refuse to move.
Headlines Tell Only Half the Story
The last two years were full of convincing headlines. AI would hollow out white-collar jobs. India had no real AI play. IT was broken and pharma was hostage to Washington.
Some of this is real. India’s five largest IT services companies reported their first combined fall in headcount in about two decades in FY26. But the claim that India has nothing to offer in AI turned out to be incomplete. Goldman Sachs recently identified 42 listed Indian companies supplying power, data centres and hardware to the AI build-out. As a group they have risen about 60% this year, largely on earnings, while the Nifty has fallen.
That is no reason to chase a theme, since much of the optimism is already priced in. The real lesson is that a sweeping narrative is not an investment thesis.
The same nuance runs through other sectors. FMCG faces softer demand in pockets, not a collapse of Indian consumption. Pharma companies with heavy US exposure face tariff and pricing uncertainty, although generics have so far stayed outside the 100% US tariff on patented medicines. But the Govt policy has not been a headwind. The GST rationalisation of September 2025, lowered rates on many everyday goods. The market barely paused to reward the move.
Markets rarely move on one clean story.
Why Foreign Money Walked Away
The world has turned less friendly. Brent crude, in the $60s a year ago, has crossed $100 more than once in 2026 after war broke out involving Iran. The US Federal Reserve, expected to cut rates this year, raised the rates in September instead, and the Bank of Japan has lifted its policy rate to 1.25%, the highest in 31 years. From an investing perspective, India has run into three pain points.
The first is the risk-free rate. The US 10-year Treasury yield has climbed above 5%, is the highest since 2007. When safe American government bonds pay more than 5% in dollars, an institutional investor naturally asks why they should take on emerging market risk, and a weakening rupee, for a premium that is uncertain at best. The bar India must clear has simply been raised.
The second is relative earnings. India’s earnings have not disappointed. Nifty 50 profits grew about 18% in the June quarter, the fastest in ten quarters and well ahead of estimates, and the current quarter looks steady too. The difficulty is that foreign investors do not judge these numbers in isolation. They compare them with what other markets offer, and on that comparison, India no longer stands out. Consensus expects MSCI India earnings to grow about 13% in 2027, the slowest among major peers including China, Korea and Taiwan, where the AI boom is lifting profits at a pace India’s index cannot match.
The third is a change in the character of the money itself. For much of the past two decades, a large share of foreign capital in Indian equities was patient. Long-only funds, pension money and sovereign investors allocated to India on structural grounds: a young and growing population, dependable earnings growth, and a broad index spread across banks, consumption, technology, industrials and energy. They bought in and stayed. Over the last few quarters, much of that money has started to behave like a venture capital fund, concentrating in the handful of businesses where growth is fastest and most visible. India’s earnings did not falter; they were outpaced. The result has been a migration towards some of the most concentrated markets in the world. TSMC alone accounts for more than 40% of Taiwan’s benchmark index and close to 57% of the MSCI Taiwan index that foreign funds track. In Korea, Samsung Electronics and SK Hynix together make up more than half of the KOSPI’s market value.
These investors think a few big winners are a better and safer bet than India’s steady, broad growth. But depending on one or two companies is much riskier than spreading money across many. What this money is chasing is also narrower than the AI economy. It wants AI earnings that show up in listed companies. China illustrates the difference. The country is central to the AI supply chain, from frontier models to the rare earths and critical minerals the hardware depends on, yet the Shanghai Composite remains around a third below the peak it set in October 2007, nearly two decades ago. Being part of a growth story has not translated into returns for China’s shareholders, and global capital knows it. For now, the money is going where growth is concentrated, visible and listed, and that means Seoul and Taipei.
Put these together and the outcome follows: foreign investors have pulled more than $45 billion out of Indian equities since the end of 2024. Look at what they sold, though, and the picture becomes more nuanced. The selling has been concentrated in large caps. By June 2026, foreign ownership of Nifty 50 companies had fallen to a 14.5-year low of 21.1%, and the share of foreign portfolios held in India’s largest companies had dropped to a six-year low. Over the same period, foreign investors have been adding to mid-caps and, more selectively, to smaller companies. By December 2025, their ownership of the Nifty Midcap 150 had reached a multi-year high of 16.4%, almost level with the 17.3% held by all domestic institutions combined, and in selected companies their stake runs well above that average. This complicates a popular view on social media that mid and small caps are being held up by fund managers deploying Indian investors’ SIP money. That view is partly right, since domestic mutual funds now own a record share of Indian equities, but it leaves out a large part of the picture. Foreign funds have built these positions knowing that the failure rate among smaller companies is high and that liquidity is thin, which makes exiting a large holding slow and costly. They have accepted those risks because the growth is visible. The same logic that took money to Seoul and Taipei is now being applied within India.
None of these pain points says Indian businesses are broken. Foreign investors themselves, through what they have chosen to keep buying, suggest the opposite. What the data does say is that India has become, for now, less exciting than the alternatives. That is a judgement about relative appeal and timing and says little about India’s long-term prospects. Foreign investors have been net buyers of Indian equities in 20 of the last 27 years, and judgements of this kind have a habit of changing when the cycle turns.
What Kept India Standing
Through all of this, India’s own savers held the line. SIP contributions reached a record ₹32,297 crore in August 2026, and domestic institutions have repeatedly bought what foreign investors sold. The economy has held up too, growing 7.8% in April to June 2026.
The fiscal picture needs a clear-eyed view. Counting the centre and the states together, India’s deficit is around 7% of GDP, which limits how far the government can cushion shocks like costly oil. It is a constraint worth respecting, though not a reason for alarm.
The market has taken all of these pressures without breaking. The harder question is whether investors can do the same.
The Hardest Part Now Is Psychological
For investors who entered equity funds during the peak optimism of 2023-2024, the primary challenge today is a psychological double-whammy: modest portfolio returns paired with everyday real-world economic pressures—such as corporate job security concerns, conservative salary increments, and sticky household inflation.
This friction naturally triggers defensive behavior: “Should I just stop my investments and save whatever cash I can?”
Market history offers an essential lesson here. Equity market returns are never distributed evenly across a timeline. Some phases are heavily front-loaded; others undergo multi-year periods of digestion. Conversely, these exact phases of weak or sideways returns frequently build the fundamental groundwork for the next major leg up.
The most critical distinction an investor can make right now is between uncertainty and permanent structural damage. Uncertainty is a permanent, non-negotiable feature of equity markets. Real portfolio damage, however, almost always occurs when an investor makes a permanent emotional change to a long-term strategy because of temporary macro uncertainty.
What Should Investors Do?
The message for mutual fund investors is clear: accept that this is a phase of normalization and moderate returns, keep asset allocation at the absolute centre of your plan, and avoid chasing changing styles.
To survive a time correction comfortably, deploy this practical execution framework:
- Mandate a Strict Liquidity Buffer: While a standard six-month emergency fund is acceptable for secure corporate households, families with high fixed debt commitments, business exposures, or variable income streams should scale this safety bucket. Holding up to three years of essential expenses in safe liquid avenues provides the financial breathing room needed to leave your long-term equity mutual funds untouched.
- Rebalance Asset Allocation Deliberately: Do not allow your equity exposure to remain unsustainably high or skewed simply because one specific thematic or mid-cap segment went vertical in the recent past.
- Stop Chasing Yesterday’s Winners: Pulling money out of a temporarily underperforming fund to chase a sector that has recently broken records feels comforting, but the switch usually happens right when that sector’s valuations have fully peaked.
- Ditch the Need for Predictions: AI trends, global geopolitics, crude oil, and central bank interest rates will rotate infinitely. A robust, well-constructed mutual fund portfolio is engineered to weather these cycles without requiring a perfect macro forecast.
Nobody can predict what happens next. A sound plan and the patience to stick with it matters far more to be successful in investing.
Ara Financial Services Pvt. Ltd.
AMFI-Registered Mutual Fund Distributor (ARN-76035) | APMI – Registered PMS Distributor (APRN02933)
Mutual Fund investments are subject to market risks. Please read all scheme related documents carefully before investing.
The views expressed in this article are educational in nature and should not be construed as personalised investment advice or as a recommendation to buy, sell or hold any security or scheme. Past performance may or may not be sustained in future. Market data as of 30 September 2026.
Shreedhara is the Founder & Director of Ara Financial Services Pvt. Ltd. He has an experience of over 2 decades in Financial Service Industry with majority of it in guiding individuals and institutions on their investments requirements.